Accenture (ACN) is one of the largest consulting and IT service providers in the world. It helps large corporations, governments, and organizations implement technologies & business strategies.
However, the stock price is down almost 50% over the past 5 years. The biggest concern among investors is the threat that AI could potentially replace its services.
But is this fear justified or did the stock just become more attractive?
In this Accenture stock analysis, we’ll break down the business using my simple, fundamentals‑driven stock analysis approach to find out whether it deserves a place in a long‑term, disciplined portfolio.
Let’s dive in.
Full disclosure: I don’t own Accenture stocks at the time of writing this analysis.
⚡Key Takeaways
- Accenture is a global market leader for technology consulting.
- The business has solid fundamentals: steady growth, strong cash flows, and low debt.
- Fair value estimate suggests the stock is within the fair price interval.
- Final take on Accenture: worth adding to watchlist!
What Does Accenture Do?
Accenture is a USA founded company that provides consulting and outsourcing services with high expertise in IT solutions.
Consulting is about innovation and transformation projects, while outsourcing is about operating and managing specific technology or business functions on behalf of the client.
It offers services related to strategy & business, technology integration, change management, IT operations, business process outsourcing, and application maintenance, among others.
The company has strategic partnerships with SAP, Microsoft, Oracle, Salesforce, AWS, Google, and many more, to help implement and support their products to corporate clients worldwide.
Stock Price Long‑Term Trend
Accenture’s long-term stock price chart shows a remarkable 1,078.4% return in 25 years. That’s almost 11$ today for every 1$ invested back then.
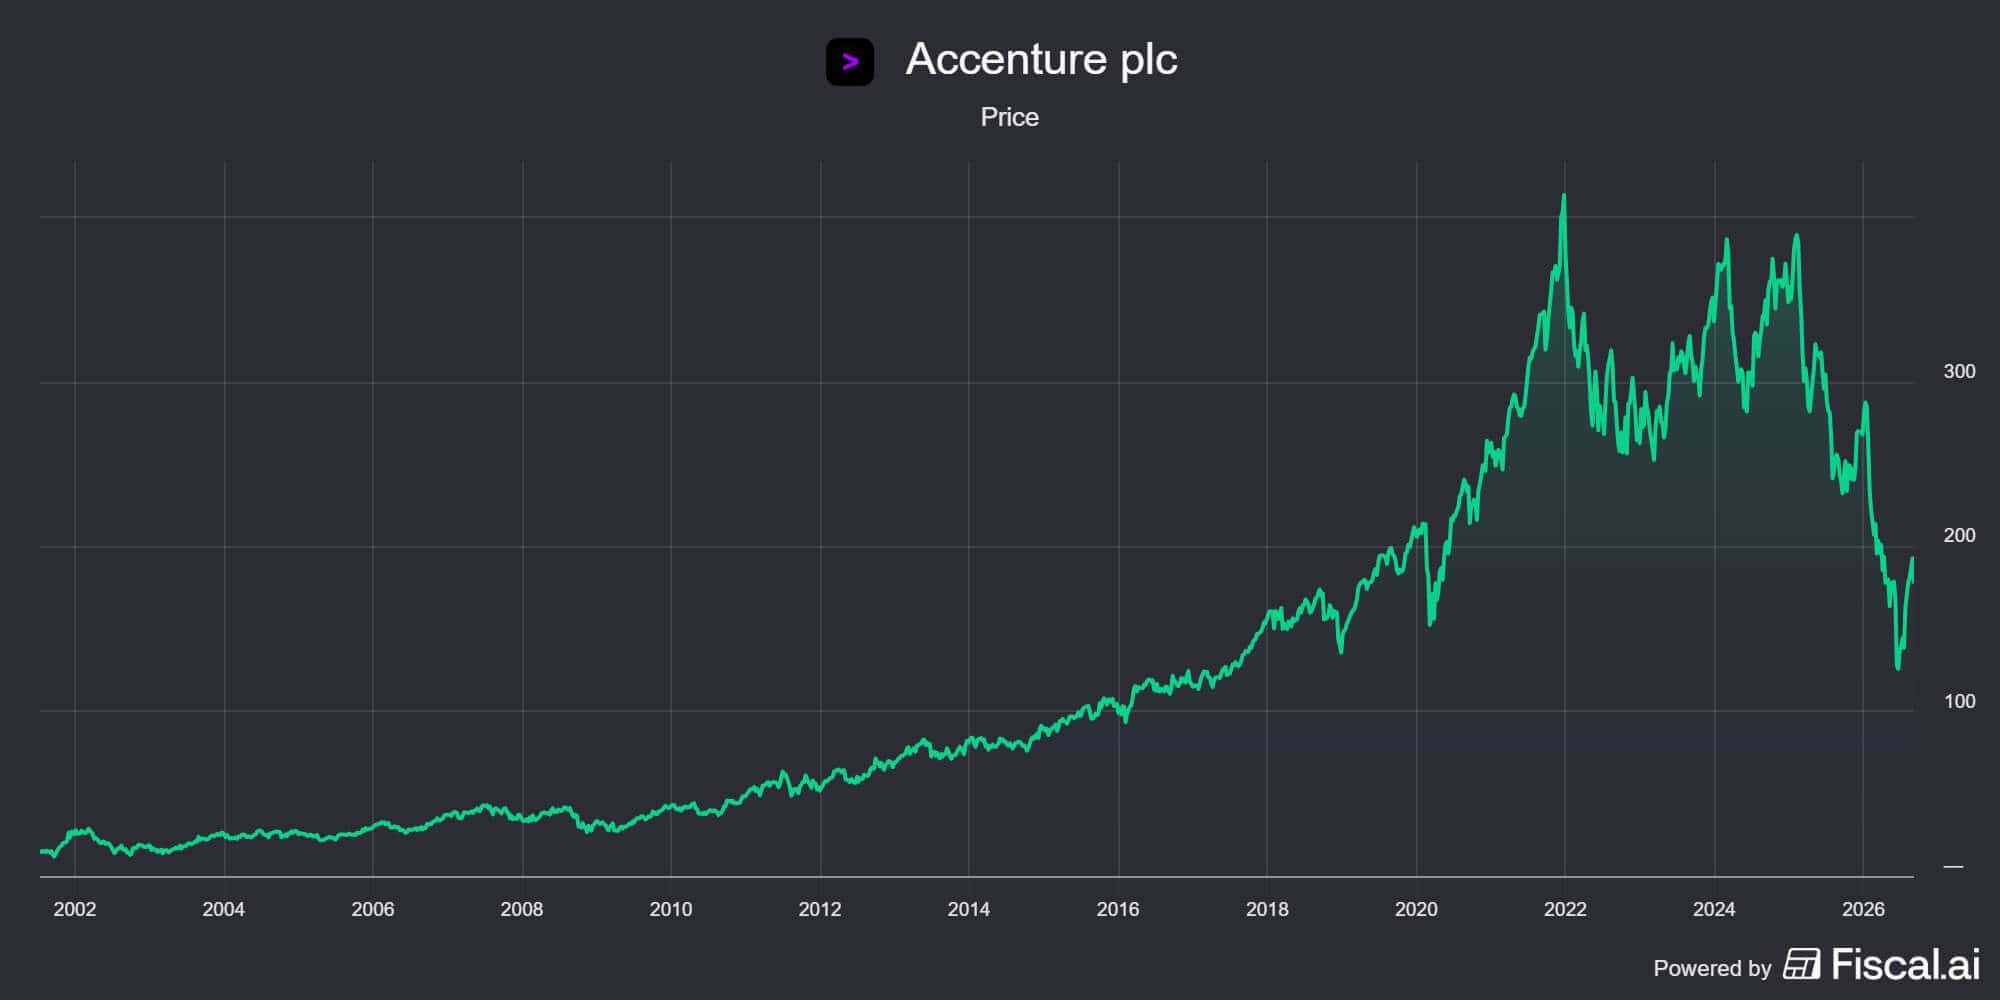
But since its early 2022 highs, the stock has faced significant downward pressure due to a combination of macroeconomic spending cuts and the threat of AI-driven disruption.
So, is Accenture really in trouble or is this a good opportunity to buy the stock? Let’s have a look into the numbers to find the answer.
Accenture Fundamental Analysis
Let’s explore the fundamentals of Accenture then.
1. Past Performance
Revenue
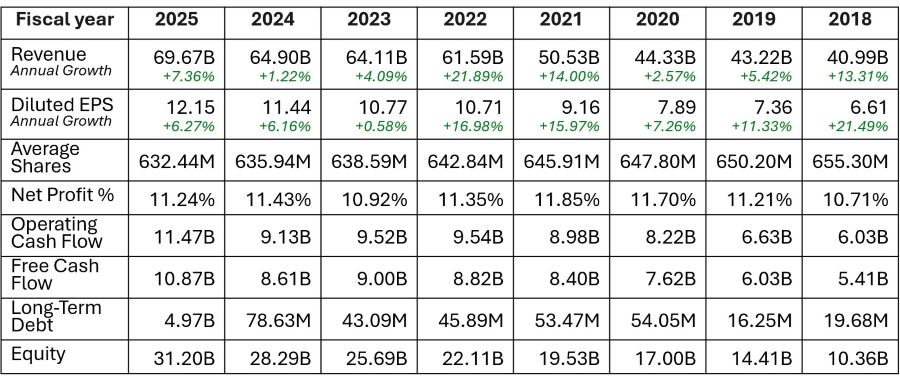
Revenue has increased 70% between 2018 and 2025, from $ 60.99B to $ 69.67B. It’s annualized 10 years revenue growth sits at 7.9%. There’s no clear trend here except that it’s always growing.
Earnings Per Share
Accenture’s earnings per share behaved in a similar way to its revenues, nearly doubling between 2018 and 2025. The annualized 10 years earnings growth was 7.8%.
Share Count
The number of shares outstanding in the market has been reduced by around 3.5% over the same period. That’s not enough to meaningfully improve the earnings for the remaining investors.
Net Profit Margin
The company’s profit margins have been consistently around 11-12%. That’s quite average for the industry.
Cash Flow
Both operating and free cash flows show a clear upward trend, having nearly doubled from 2018 to 2025.
This is well aligned with revenue and earnings expansion showing that Accenture can efficiently scale its operations and convert growth into cash.
2. Financial Health
The company is in a strong financial position and has historically operated with an exceptionally clean balance sheet, carrying virtually no long-term debt.
In 2025, debt jumped to $ 5B but still that makes only for 16% debt-to-equity ratio which is very low. Tho that was enough to fund its acquisition strategy in the artificial intelligence and automation space.
3. Dividends
Accenture pays a forward dividend of $ 6.52 per share, yielding a notable 3.6%. And it has delivered a consistent and increasing dividend for more than twenty-five years, making it a reliable income payer.
4. Growth Outlook
Time to jump into my educated guesstimate on Accenture based on past performance and recent trends.
Although the stock price is struggling, the fundamentals don’t show signs of distress. I don’t believe AI will be a threat to the business but rather become a growing revenue stream.
Everybody needs to figure out how to effectively integrate AI into their business for it to actually drive results. That’s not something most will manage to do without external support.
Accenture is well positioned to leverage its partnerships, expertise, and financial strength into the future, whatever new disruptive technologies may come.
For all that, I would expect a moderate 6-10% annual earnings growth over the coming years.
Accenture Fair Value Estimate
Now let’s run our back-of-the-envelope valuation to get a quick and simple assessment.
Owner’s Earnings
First, let’s estimate the total potential return on investment by using the owner’s earnings:
Expected return = future EPS growth (6–10%) + dividend yield (3.6%) ≈ 10–14% per year
If the stock is fairly priced, this is the return an investor might expect.
PEG Ratio
Next, let’s assess whether the stock is trading at a fair price or not.
Just by comparing the current P/E ratio (TTM) of 14x with our owner’s earnings estimate of 10–14% we can see that the stock seems fairly priced:
PEG = P/E ÷ Owner’s earnings = 1.4 to 1.0
From the growth at a reasonable price approach, we know that a PEG equal to 1 suggests that the company is reasonably priced compared to its expected return.
Fair Value Estimate
So, if Accenture was priced in line with its growth (PEG ≈ 1), its P/E should be between 10-14x versus today’s 14x.
This implies the stock currently trades at somewhere between fair price and a 29% premium versus our fair value estimate.
Conclusion: Is Accenture a Good Investment?
Here’s my final take on Accenture: a great company, near fair price, and definitely worth adding to our watchlist.
Why? Let’s recap everything.
Does the Company Have Solid Financials?
Yes. Accenture is a revenue and profit growing company while keeping a decent profit margin. It generates positive and growing cash flows that lead to a strong cash position and low levels of debt.
Do I Understand the Business Model?
Yes. Accenture is a trusted professional services provider that impacts how companies all over the world innovate and operate. It’s expertise, reputation, and acquisition strategy makes it hard to imagine a future where they would not continue to do well.
Does It Trade at a Fair Price?
Yes. Based on this simple stock analysis, we can say that Accenture is within the fair price interval relative to its expected growth.
👉Action step: Take another look at Accenture using your own assumptions. Do you agree with this assessment, or do you see something I’ve missed? Share your thoughts in the comments — I’d love to hear your perspective.
And if you haven’t yet, subscribe for more fundamentals‑driven stock analyses.