Deckers Outdoor (DECK) is a global footwear and apparel company based in California, USA. It designs, markets, and distributes casual lifestyle and high-performance products under well-known brands such as UGG and HOKA.
The company seems to be transitioning into a growth deceleration phase, and the stock price has been in free-fall since the beginning of 2025.
So, is this a good investment or a value trap?
In this stock analysis, we’ll break down the business using my stock analysis framework to find out whether it deserves a place in a long‑term, disciplined portfolio.
Let’s dive in.
Full disclosure: I don’t own any Deckers Outdoor stocks at the time of writing this analysis.
⚡Key Takeaways
- Deckers Outdoor is a casual lifestyle and high-performance footwear company.
- The business might be slowing down but still offers great balance sheet and cash flow.
- Fair value estimate suggests the stock is within the fair price interval.
- Final take on Deckers Outdoor: worth adding to our watchlist!
What Does Deckers Outdoor Do?
Deckers Outdoor operates a brand-builder and asset-light business model focused on designing, marketing, and distributing premium performance and lifestyle footwear and apparel.
The company’s brand portfolio includes:
- HOKA: high-growth performance running, trail, and outdoor footwear that has become the company’s primary growth engine.
- UGG: iconic seasonal lifestyle and comfort footwear (boots, slippers) that remains a major high-margin revenue and profit driver.
- Other brands: includes Teva (outdoor/casual sandals), Sanuk (laid-back lifestyle footwear), and Koolaburra by UGG (more accessible price points).
Production is outsourced to independent third-party contract manufacturers, keeping capital expenditures low and focusing internal efforts on design, brand storytelling, and marketing.
Deckers sells its products globally through direct-to-consumer channels, wholesale partners, and its own retail stores.
Stock Price Long‑Term Trend
Deckers’ long-term stock price chart shows an incredible 6,887.7% return since 1993, that’s a 13.7% annualized growth. But the stock suffered a painful drawdown of +60% from its all-time high in early 2025.
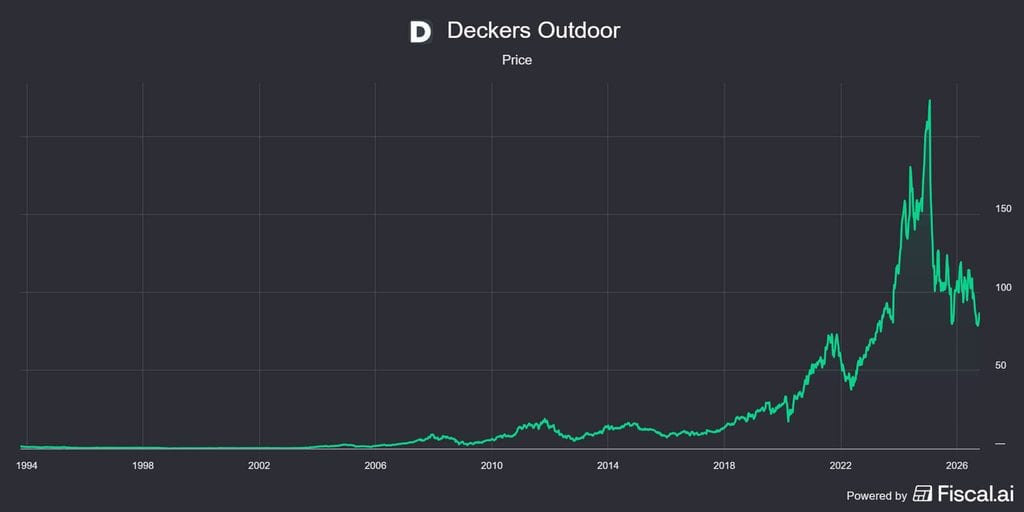
Seems like investors have fallen out of love with the stock and who knows if this is the bottom already.
But the bigger question is whether the market negativity is fully justified or not.
Let’s have a look into the numbers to find our answer.
Fundamental Analysis
Let’s explore the fundamentals of Deckers Outdoor.
1. Past Performance
Revenue
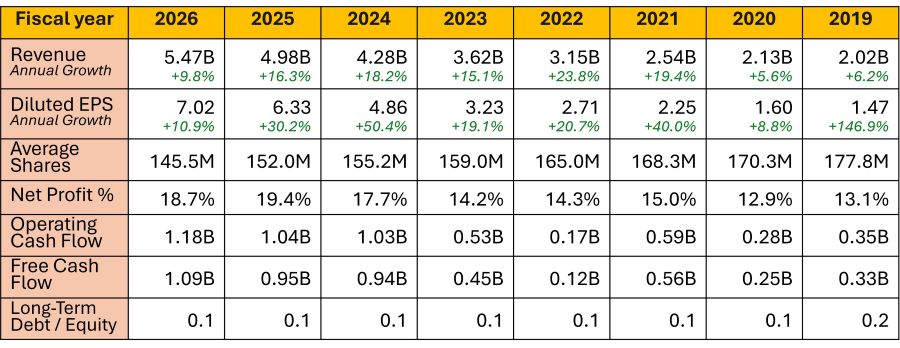
The company’s revenue has almost tripled between 2019 and 2026, from $2.02B to $5.47B, that’s a yearly growth of 15.3%. But for the last three years growth is losing its power.
Earnings Per Share
Earnings per share have performed even better, increasing by nearly 4x times over the same period. However, they’re much more explosive and much less predictable.
Share Count
Consistent buybacks have reduced the number of shares outstanding in the market by 18.1% over the past eight years. That helped boost its earnings per share performance.
Net Profit Margin
The company’s profit margins have improved considerably, from around 13% up to around 19%.
Cash Flow
Both operating and free cash flows show a clear upward trend, having more than tripled from 2019 to 2026. That’s the effect of having a capital-light business model.
Deckers was able to accumulate a growing cash position and finance its shares buybacks as a result.
2. Financial Health
The company is in a great financial position and continues to run on a clean balance sheet. Debt-to-equity ratio is just around 10%.
3. Dividends
Deckers Outdoor does not distribute dividends and it’s not likely to do it any time soon. The preferred alternative has been its shares buyback initiatives.
4. Growth Outlook
Time to jump into my educated guesstimate on Deckers Outdoor based on past performance and recent trends.
The business has enjoyed a fast growth cycle that seems to be slowing down.
Both HOKA and UGG have opportunities for greater distribution, geographic expansion, and extensions into new categories. However, they’re known for specific styles of footwear that could fall out of favour with consumers or may be reaching their full potential.
For that reason, I would expect an acceptable 12-15% annual earnings growth over the coming years.
Deckers Outdoor Fair Value Estimate
Now let’s run our back-of-the-envelope valuation to get a quick and easy assessment.
Owner’s Earnings
First, let’s estimate the total potential return on investment by using the owner’s earnings:
Expected return = future EPS growth (12–15%) + dividend yield (0%) ≈ 12–15% per year
If the stock is fairly priced, this is the return an investor might expect.
PEG Ratio
Next, let’s assess whether the stock is trading at a fair price or not.
When we compare the current P/E ratio (TTM) of 12x with our owner’s earnings estimate of 12–15%, we can see that the stock seems fairly priced:
PEG = P/E ÷ Owner’s earnings = 1.0 to 0.8
From the growth at a reasonable price approach, we know that a PEG equal to 1 suggests that the company is reasonably priced compared to its expected return. And below 1 suggests undervaluation.
Fair Value Estimate
So, if Deckers Outdoor was priced in line with its growth (PEG ≈ 1), its P/E should be between 12-15x versus today’s 12x.
This implies the stock currently trades at somewhere between fair price and a 20% discount versus our fair value estimate.
Conclusion: Is Deckers Outdoor a Good Investment?
Here’s my final take on Deckers Outdoor: worth adding to our watchlist.
Why? Let’s recap everything.
Does the Company Have Solid Financials?
Yes. Deckers Outdoor is a revenue and profit growing company with an expanding profit margin. It generates positive and growing cash flows that lead to a strong cash position and low levels of debt.
Do I Understand the Business Model?
Yes. Deckers Outdoor is a global footwear and apparel company responsible for brands such as UGG and HOKA. Production is outsourced, keeping capital needs low, and distribution is done via wholesale and direct-to-consumer channels.
Does It Trade at a Fair Price?
Yes. Based on this simple stock analysis, we can say that Deckers Outdoor is within the fair price interval relative to its expected growth.
👉Action step: Take another look at Deckers Outdoor using your own assumptions. Do you agree with this assessment, or do you see something I’ve missed? Share your thoughts in the comments — I’d love to hear your perspective.
And if you haven’t yet, subscribe for more fundamentals‑driven stock analyses.